Finland: when the withdrawal of Russian buyers weakens the property market
In the east of the country, the closure of trade with Russia is transforming demand. But the fall in Finnish property prices is also explained by interest rates, employment and available supply. An illuminating case for understanding a territory’s dependence on outside buyers.

Gaston michelin
Agent immobilier
A border is not just a line on a map. For a property market, it can represent visitors, jobs, second homes and buyers able to support certain transactions. Eastern Finland has been experiencing this since relations with Russia broke down following the invasion of Ukraine. Demand has changed, purchase conditions have tightened and some assets have lost part of their usual clientele. This change must, however, be placed within a national market that is itself going through a difficult period.
A market still heading downward this autumn
According to preliminary data published on 28 October by Statistics Finland, prices of existing dwellings in housing companies fell 2.2% year on year in September 2026. Trends remained mixed: Espoo showed a fall of 4.4% and Turku 3.6%, while Oulu rose 2%. [1]
The scope deserves clarification. These statistics cover dwellings held in housing companies, a common form of ownership in Finland. They do not correspond to a single index of all houses, all land and all commercial buildings. A French reader should keep this difference in mind before directly comparing the figure with a national indicator for existing homes.
Above all, the falls seen in large cities far from the border show that the Russian factor does not sum up the situation. To explain a market, one must distinguish a local demand shock from the economic conditions common to the whole country.
The east of the country has lost part of its outside demand
In its spring 2026 study, Nordea explicitly mentions the withdrawal of Russian buyers as a factor reducing demand in eastern Finland. The same document also highlights the effects of interest rates, rising housing costs, a weak economy and abundant supply in some segments. [2]
The local mechanism is easy to understand. A property aimed at a second-home or investment clientele does not automatically find a resident buyer when that clientele disappears. Needs, resources and location criteria can be very different. A territory must then re-examine the possible use of its housing stock as much as its prices.
The effect can also be transmitted through economic activity. Fewer passers-by and visitors can weaken shops, accommodation and services. For commercial premises, the number of potential customers and the operator’s ability to pay rent become decisive variables. This chain has to be studied business by business; it is not a flat discount attached to a whole region.
Acquisitions are now more tightly regulated
A legislative change that came into force on 15 July 2025 tightened restrictions on certain property acquisitions. The national land survey indicates that permits are currently not granted to the Russian or Belarusian nationals and entities concerned, with exceptions linked in particular to certain permanent residence permits. [3]
The stated aim is national security. Even so, the reach of a permit regime depends on the buyer’s situation and the legal form of the transaction. A rule on acquiring a building should not be summed up in a formula that assumes all homes and all foreign buyers are treated identically.
Information published by Yle in January 2026 also shows that Russian acquisitions had still taken place after the new provisions came into force. Exceptions, holding structures and registration delays complicate the immediate reading of the figures. Legal restriction, falling demand and the number of sales actually recorded must therefore be kept separate. [4]
Why cutting the price may not be enough
When a seller no longer receives viewings, they may be tempted to think only in terms of a percentage price cut. Yet if the property’s original use matched a clientele that has gone, the problem may run deeper. A residence far from jobs, schools or services does not necessarily become suitable for a local household just because it costs less.
The same reasoning applies to a commercial asset. Before deciding on a rent reduction, the owner should examine the activities still conceivable, the technical condition, operating costs and the authorisations needed. Renovating or converting can provide an answer, but only if the new use meets real demand.
Liquidity then becomes an essential component of value. Two properties listed at the same price can have very different prospects if one usually finds a buyer within a few months and the other needs a much longer search. The cost of that wait must be built into charges and financing.
A useful method for any purchase in a dependent market
The first check is to identify the end users. Are they residents, employees, students, tourists or an international clientele? A territory can combine several sources of demand; that diversity offers more options when one of them contracts. It must nevertheless be demonstrated by local observation.
The second step concerns the holding budget. Heating, maintenance, shared charges and works can weigh heavily on a home with an attractive purchase price. The owner must be able to keep the property if letting or resale times lengthen. A small initial outlay never removes the need to assess recurring expenses.
Finally, signed prices and actual uses must be compared. Old listings, sometimes kept up despite very weak demand, give an imperfect picture of the market. Completed sales, sustainable rent levels and technical documents provide a firmer basis for deciding.
What Finland teaches French owners
The Finnish case does not allow a similar development in France to be predicted. It does, however, recall that part of property value depends on factors external to the building: mobility, foreign clientele, economic activity and acquisition rules. A lasting change in these conditions can alter the number of buyers as much as their budget.
To assess a portfolio, the useful question is therefore that of its dependence. Who wants to use this property today, and what other demand could take over tomorrow? Studying these uses complements the analysis of square metres. It makes it possible to judge an opportunity on its ability to remain useful in several contexts.
Sources
[1] Statistics Finland - Housing prices, September 2026 - 28 October 2026; preliminary data
[2] Nordea - Finland Housing Market Review, Spring 2026 - Spring 2026
[3] National Land Survey of Finland - New permit rules - 21 July 2025; in force from 15 July
[4] Yle - Russian purchases after the restrictions - 4 January 2026, updated 5 January
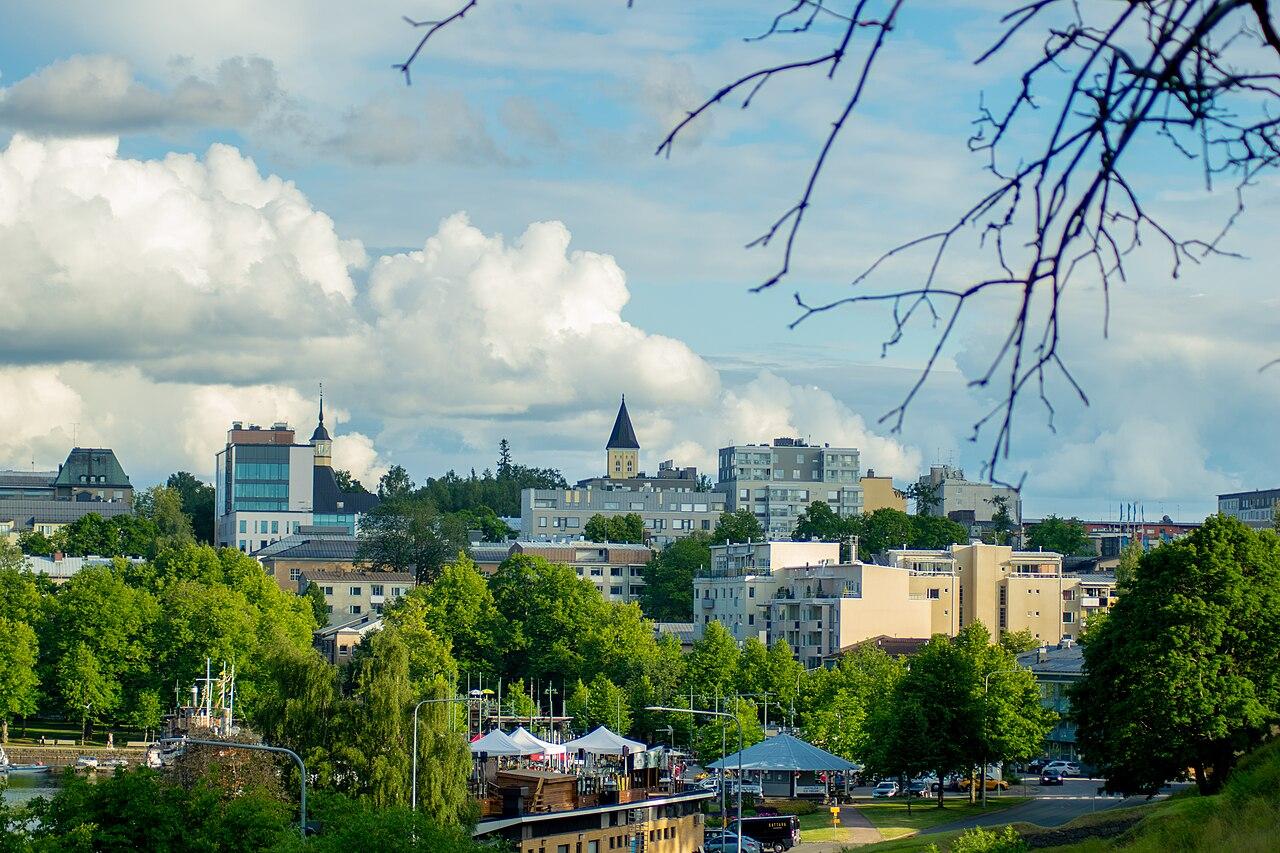
Photo credit: Toni, Lappeenranta Landscape.jpg / Wikimedia Commons — CC BY-SA 4.0. Panorama of Lappeenranta on 10 July 2020, before the border closures discussed in this article; image resized by the source.