Looted shops in Paris: who really pays for the damage?
After the October 2026 damage, restoring a shop raises very real-estate questions. Insurance, lease, co-ownership and resuming trading: how to organise decisions and stop the loss from weakening the premises over the long term.

Gaston michelin
Agent immobilier
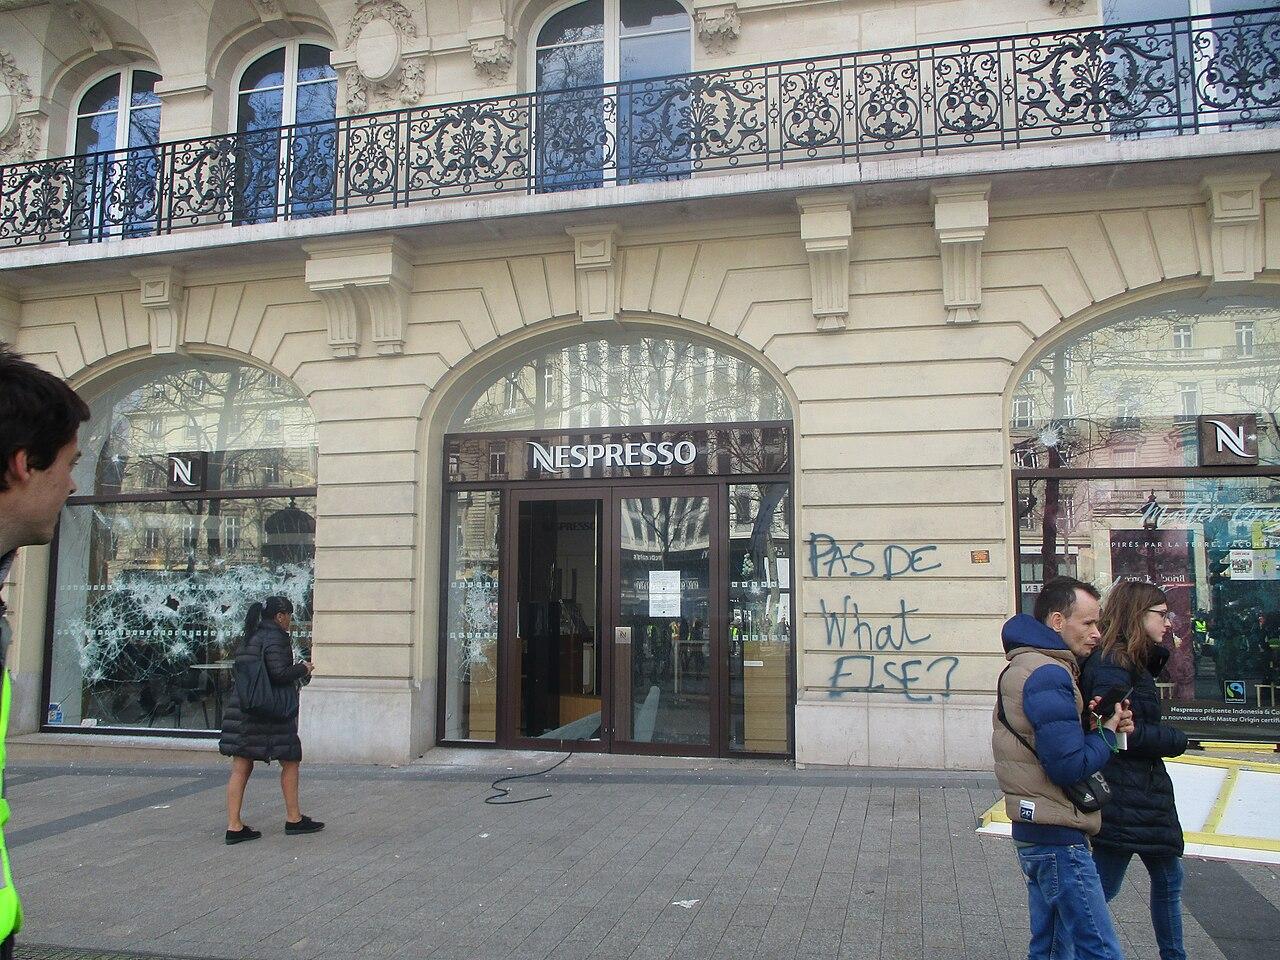
A smashed shopfront immediately catches the eye. Yet for the owner of the walls as for the shopkeeper, the consequences go far beyond replacing a pane of glass. Access must be secured, damaged items identified, work shared out and reopening made possible. Meanwhile, charges keep running and cash flow can tighten. The violence of 17 and 18 October 2026 in Paris is a reminder of one reality: a commercial unit is at once a building, a contract and a working tool. These three dimensions must be handled together.
A recent event, responses to coordinate
The Île-de-France prefecture announced support measures for affected businesses: assistance, payment facilities and schemes designed to protect activity. The City of Paris has also stepped in to help the damaged shops. These announcements answer an economic emergency; they do not, on their own, settle how responsibilities are shared within each building. [1]
From the first exchanges, it is useful to bring together the landlord, the tenant and, where common areas are affected, the managing agent. A shop window, a metal shutter, a sign and a façade can fall under different perimeters. A single global quote, accepted too quickly by one party, risks mixing works whose funding must be kept separate.
Insurance operates within the terms of the contract
France Assureurs points out that damage caused by urban violence may be covered by the “riots and popular movements” guarantee, depending on the cover and levels taken out. Fire, theft and glass breakage do not describe exactly the same losses. The excess, the ceilings and the supporting documents required must therefore be checked before any expense is treated as reimbursed. [2]
The shop’s insurance, the owner’s insurance and the building’s insurance are not three refunds that can be stacked for a single invoice. How they fit together depends in particular on the property insured and the circumstances. The first task is to obtain a written position from each insurer: which damage is it examining, which documents does it require and who appoints the expert?
Closure raises a second question. Optional business-interruption cover may compensate a loss of gross margin under the terms of the contract; it does not automatically equal the full turnover lost. A shop closed for several weeks should therefore have its loss established with its accounting documents, rather than multiplying the days closed by its usual takings. [2]
The lease identifies each party’s obligations
The reflex “everything is the tenant’s responsibility” is too simplistic. The clauses on repairs, fittings, insurance and the return of the premises must be re-read, then compared with the applicable rules. Who owns a piece of equipment, how it was installed and how the shopfront is classified within the co-ownership also matter.
The tenant has an interest in reporting damage to the landlord immediately, with photographs and a precise description. The owner, for their part, should avoid letting contractual uncertainty block the first protective measures. Securing the premises can be organised quickly, while keeping the evidence and reserving the discussion on who ultimately bears the cost.
An interruption of activity does not entitle anyone to improvise a rent suspension. If the use of the premises is affected, the parties should have their situation examined and formalise any agreement: duration, amount, works schedule and conditions for resumption. A clear written record protects better than a phone promise when the works drag on or an insurer disputes a guarantee.
The aid announced can speed up reopening
On 29 October the Region announced a budget of 10 million euros. Its scheme includes 5,000 euros of aid for repairs and equipment, and 2,000 euros of aid for security. With partners’ contributions, the total can reach 12,500 euros for an eligible shop. Applications are announced to open on 13 November. [3]
This ceiling should not be mistaken for a sum that is already secured. The criteria relate in particular to the size of the business, the loss, the police complaint and the insurance; the contributions that can be drawn on also depend on the local scheme. The rules on combining aid and on eligible expenses must be re-read when applying. The October 2026 aid must not be confused with the earlier 2023 campaigns.
In practice, a well-prepared file includes the police complaint receipt, photographs, original invoices, quotes and exchanges with the insurer. The CCI also recommends notifying the managing agent when the façade, the entrance hall or other common areas are affected. Keeping a shared file limits omissions and contradictory requests. [4]
Restoration is also a real estate decision
Repairing like for like is not always the only scenario to consider. The loss may lead to comparing several protection solutions or improving access. But altering a shopfront may require specific approvals or procedures. Before ordering anything, check the constraints of the co-ownership, the municipality and the business being operated.
For an investor, the stakes go beyond the cost of the works. The quality of the tenant, their ability to resume trading and the smoothness of the contractual relationship all influence the continuity of income. Responsive support can prevent a temporary closure from turning into lasting vacancy. This assessment must remain specific to the address and the business concerned.
What to remember before deciding
The damage documented in October does not, on its own, allow the conclusion that the value of Parisian shops has fallen across the board. To value a property, you still need to study its location, lease, rent and comparable transactions. The loss adds a technical and insurance file to that analysis.
The priority is to secure, document, coordinate and then put decisions into contract. For an owner of commercial premises, a precise picture of guarantees and obligations is as useful as a price estimate. LGH Patrimoine can support you with the real estate analysis of the premises and the coordination of the project, alongside the professionals competent in insurance and legal matters.
Sources
[1] Préfecture d’Île-de-France - Support for affected shops - 23 October 2026
[2] France Assureurs - Compensation for urban violence - Accessed 4 November 2026
[3] Région Île-de-France - Emergency and security fund - 29 October 2026
[4] CCI Paris Île-de-France - Shopkeepers hit by damage: procedures - Accessed 4 November 2026
Photo credit: Thomon, Paris 16 mars 2019 nespresso.jpg / Wikimedia Commons — CC BY-SA 4.0. Archive photograph from 16 March 2019: it does not show the October 2026 damage discussed in this article.